By Mission Property Loss Consultants
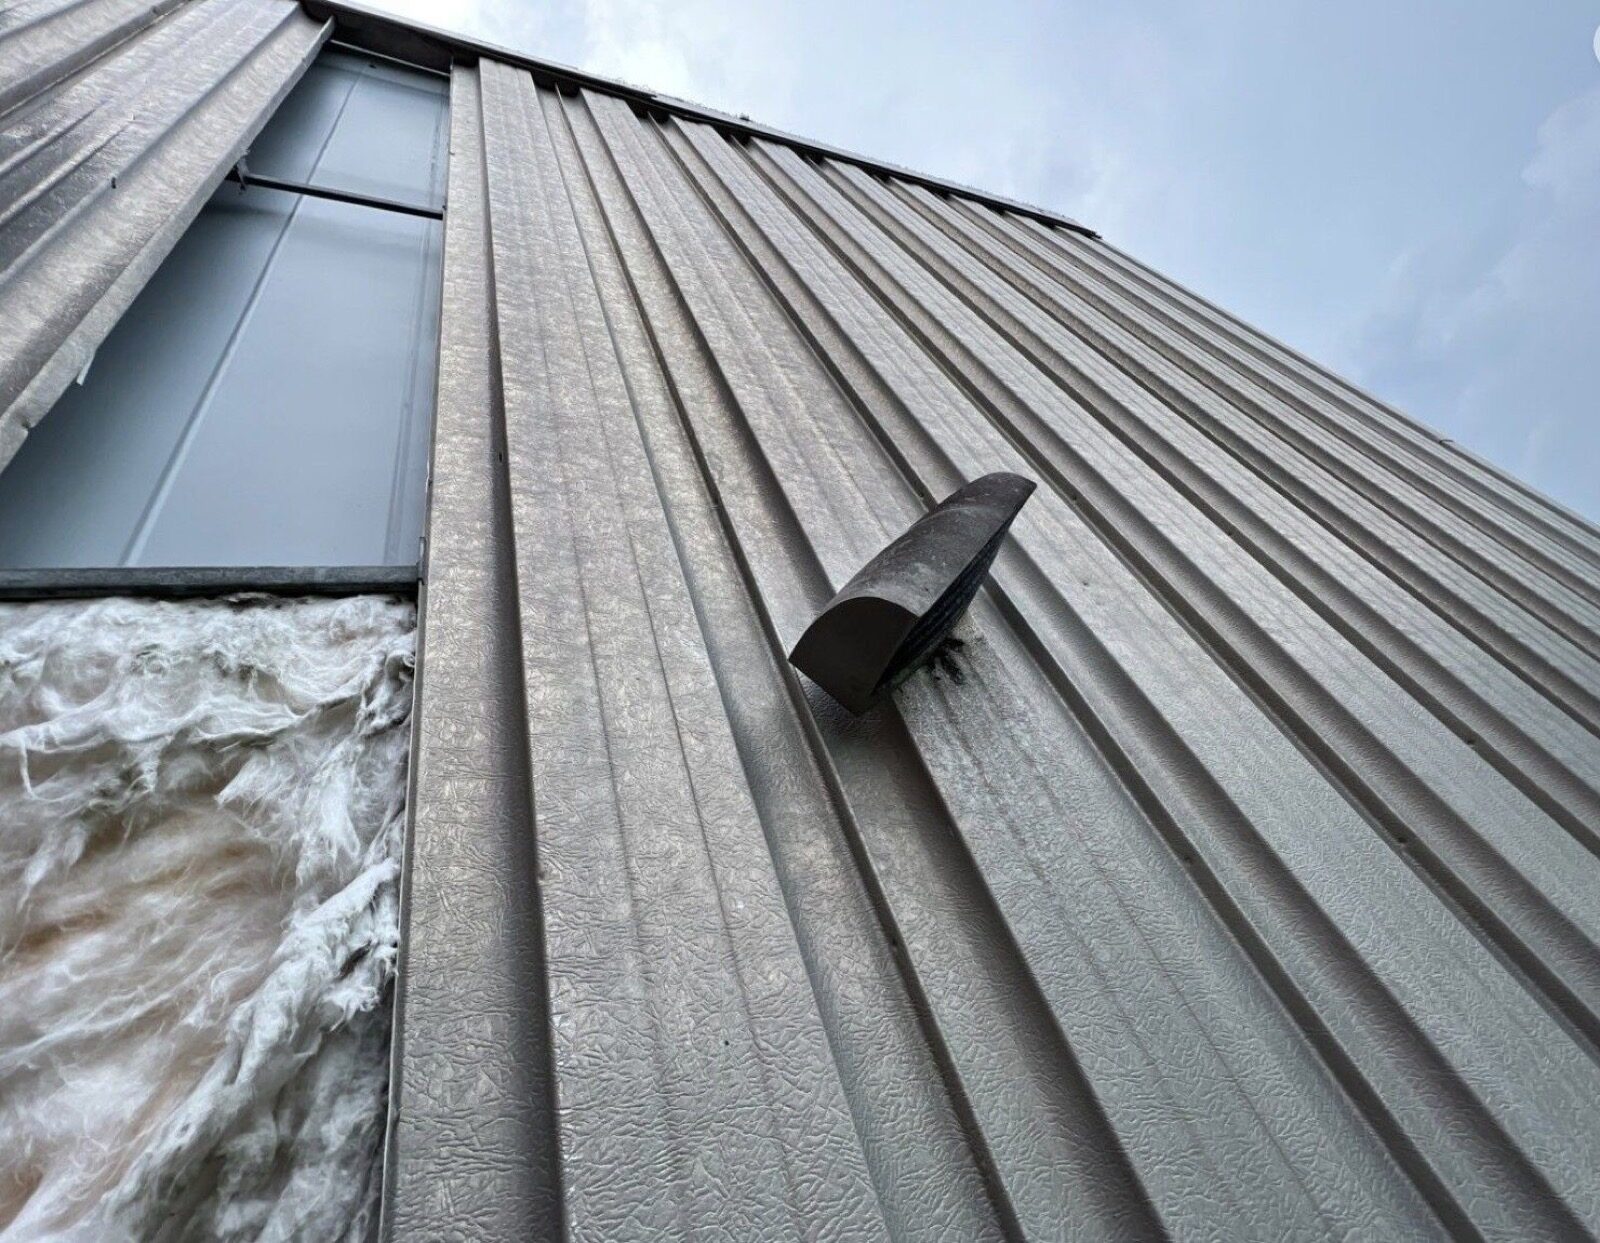
Wind damage can have a devastating impact on commercial buildings, often leading to significant financial and operational losses. Whether the result of a hurricane, straight-line winds, or a severe thunderstorm, these events can compromise roofing systems, HVAC units, windows, signage, and building exteriors. In many cases, interior water damage follows as a secondary consequence.
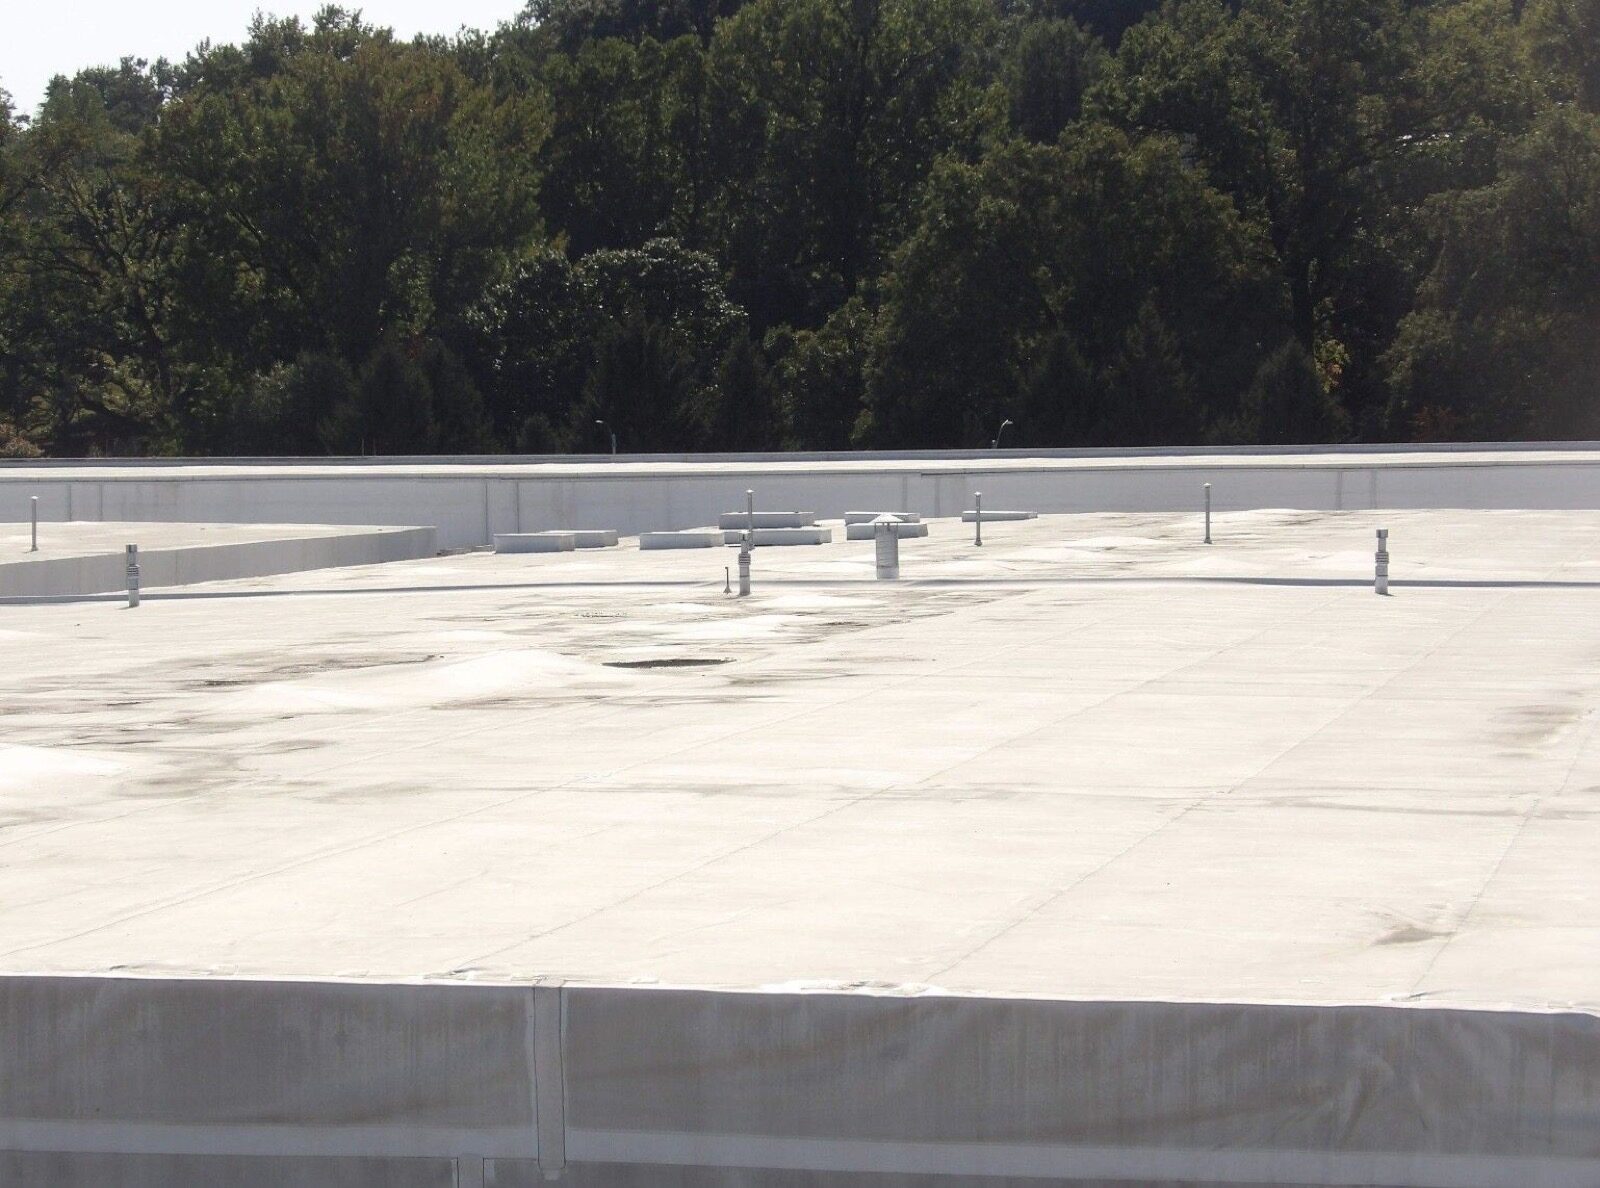
Filing a wind damage insurance claim for a commercial property is more complex than many realize. Policyholders often face challenges like inadequate carrier inspections, undervalued repair scopes, or even outright denials. That’s why partnering with a licensed public adjuster is essential.
A public adjuster represents the policyholder not the insurance company and can conduct a detailed, unbiased inspection of wind-related damage. By working with a seasoned storm damage public adjuster, you gain an advocate who understands policy language, construction costs, and code compliance. For large-scale events, especially when business interruption is involved, a large loss adjuster is invaluable in compiling documentation and negotiating fair settlements.
A well-prepared commercial property insurance claim should include a full damage assessment, a detailed repair estimate, applicable code upgrades, and documentation of any loss of income. Don’t leave money on the table hire a public adjuster to help you recover fully from wind damage.
Wind damage claim questions
What is typically damaged in commercial wind losses?
Roofing, rooftop HVAC units, windows, signage and exterior walls, and then interior water damage after openings are created.
Do wind and hail have separate deductibles?
Many commercial policies use a separate, often percentage-based, deductible for wind or hail. Check your declarations page.
What should a strong wind claim include?
A full damage assessment, a detailed repair estimate, applicable code upgrades and documentation of any lost income.
