By Mission Property Loss Consultants
Understanding Freeze Losses, Ice Damage, Frozen Pipes & Winter-Related Property Risks
Winter losses rarely happen all at once.
They develop quietly — overnight, behind walls, under roofing systems, or inside mechanical spaces — and by the time the damage becomes visible, the cost of repair is often substantial.
Freeze-related claims are among the most misunderstood and most disputed property losses affecting commercial, industrial, and institutional facilities. And unfortunately, they’re also some of the most under-documented.
This guide is intended to help property owners, facility managers, and administrators understand:
- How winter damage actually occurs
- Why these claims are frequently challenged
- What documentation matters most
- How to protect your property and your claim
Why Freeze Claims Are Treated Differently by Insurance Carriers
Unlike storm or fire losses, winter-related claims often involve:
- Gradual temperature drops
- Delayed discovery
- Hidden or concealed damage
- Questions of maintenance vs. sudden loss
- Multiple contributing causes
Insurance carriers scrutinize freeze claims heavily because coverage often depends on:
- Whether reasonable care was taken
- Whether systems were maintained
- Whether damage was sudden or progressive
- Whether proper mitigation occurred
This makes documentation and early response critical.
Common Winter-Related Losses in Commercial Properties
-
- Frozen & Burst Pipes (One of the Most Costly Winter Losses)
Frozen pipes are responsible for millions in property damage every winter and often occur in:
-
-
- Exterior wall cavities
- Mechanical rooms
- Vacant or low-occupancy buildings
- Poorly insulated risers
- Fire suppression systems
- Ceiling voids
-
When pipes freeze, expansion causes ruptures — and once temperatures rise, water discharge can be severe.
Common resulting damage includes:
-
-
- Saturated drywall and insulation
- Electrical damage
- Flooring failure
- Structural deterioration
- Mold growth
- Business interruption
-
⚠️ Important:
Many freeze claims are challenged based on whether the building was “properly heated” or “reasonably maintained.” Documentation matters.
-
-
- Snow Load & Roof Stress
-
Snow accumulation can create dangerous structural conditions, especially on:
-
-
- Flat or low-slope roofs
- Older buildings
- Facilities with rooftop equipment
- Structures with poor drainage
-
Risks include:
-
-
- Roof deflection
- Decking separation
- Structural fatigue
- Partial or full collapse
-
Snow load failures often begin subtly, long before collapse occurs.
-
-
- Ice Damming & Hidden Water Intrusion
-
Ice dams form when melting snow refreezes at roof edges, forcing water back under roofing materials.
This leads to:
-
-
- Water infiltration behind walls
- Saturated insulation
- Ceiling damage
- Mold development
- Delayed interior leaks
-
Ice dam losses are frequently underpaid because the visible damage represents only a fraction of the true impact.
-
-
- Fallen Trees & Ice-Loaded Branch Failures
-
Heavy snow and ice accumulation place extreme stress on trees and limbs, often causing:
-
-
- Roof punctures
- Structural wall damage
- HVAC and rooftop unit damage
- Fence and perimeter destruction
- Power outages and service interruptions
-
Tree-related losses are often complex because:
-
-
- Damage may occur hours or days after snowfall
- Responsibility may be disputed
- Structural damage is not always immediately visible
- Multiple coverage sections may apply
-
Proper documentation of impact, entry points, and resulting damage is essential.
-
-
- Mechanical, HVAC & Fire Suppression Failures
-
Cold temperatures frequently cause failures in:
-
-
- Sprinkler systems
- Boiler lines
- HVAC coils
- Pumps and valves
- Emergency fire protection systems
-
These losses often require:
-
-
- Mechanical analysis
- Engineering input
- Code compliance review
- Careful causation documentation
-
They are also among the most expensive freeze-related claims.
What Insurance Companies Look for in Freeze Claims
When evaluating winter losses, insurers typically assess:
✔ Was the building adequately heated?
✔ Were systems maintained?
✔ Was the property occupied or monitored?
✔ Was damage sudden or progressive?
✔ Was mitigation performed promptly?
✔ Were reasonable precautions taken?
✔ Is damage supported by documentation?
The outcome of a claim often hinges on how clearly these questions are answered.
📸 Winter Freeze Claim Photo Checklist
(Recommended for Facilities & Property Management Teams)
Exterior & Roof
☐ Snow accumulation on roof
☐ Ice buildup along eaves or drains
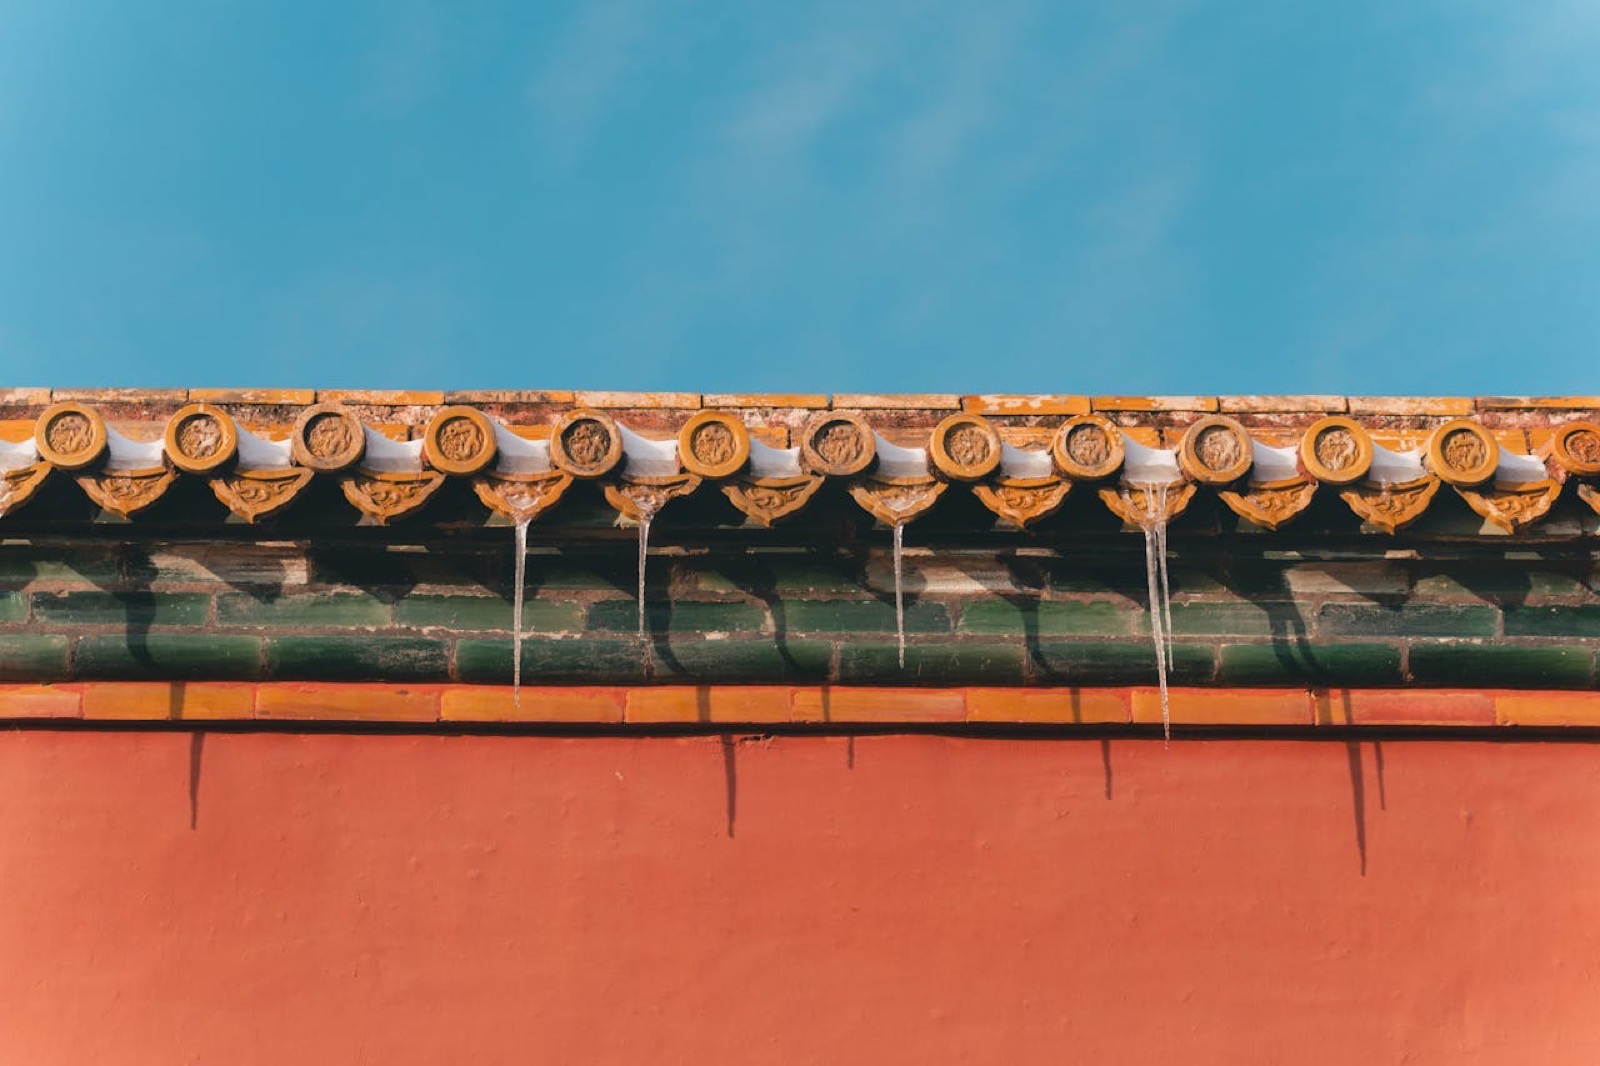
☐ Ice dams or icicles
☐ Fallen trees or branches
☐ Roof sagging or deflection
Interior
☐ Ceiling staining or collapse
☐ Water on floors
☐ Wet insulation
☐ Cracked drywall
☐ Moisture migration patterns
Mechanical / Utility Areas
☐ Frozen or burst pipes
☐ Sprinkler system damage
☐ HVAC or boiler failure
☐ Electrical exposure to moisture
Documentation
☐ Wide-angle and close-up photos
☐ Date/time stamps
☐ Temperature records
☐ Snowfall data
☐ Maintenance logs
☐ Utility outage history
📌 Do not discard damaged materials until documentation is complete.
The Most Common Mistake Property Owners Make
Waiting.
Many owners assume:
-
-
- The damage is minor
- The carrier will handle it
- Repairs can wait
- Documentation can be done later
-
Freeze claims worsen with time.
Delays often result in reduced coverage or denial.
Need Help With a Winter or Freeze-Related Claim?
Mission Property Loss Consultants
Commercial • Industrial • Institutional Claims
